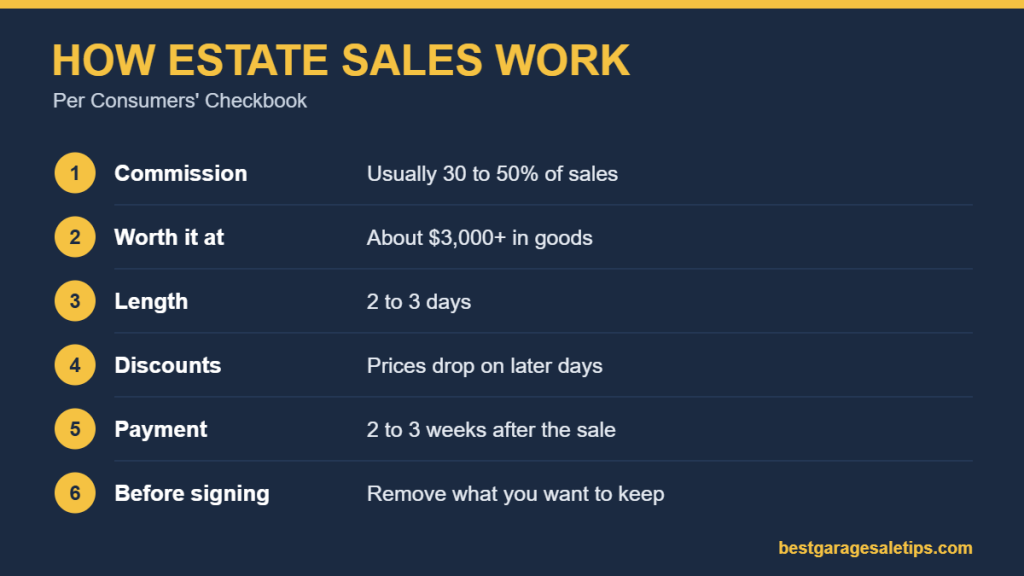
An estate sale is a sale of most or all of the belongings in a home, held inside the house over two or three days. Families usually hold one after a death, or when someone downsizes or moves into assisted living. Many hire an estate sale company, which prices everything, advertises, runs the sale and keeps a commission, typically 30 to 50 percent of the proceeds.
What makes something an estate sale?
The difference is scale. A garage sale gets rid of a few things you don’t want. An estate sale empties a whole household, from furniture, appliances and dishes to tools, clothing, jewelry, art and collectibles. Shoppers walk through the home and buy items where they sit. For a side-by-side comparison, see garage sale vs. yard sale vs. estate sale.
Does an estate sale always mean someone died?
No. Many estate sales happen because someone is downsizing, moving across the country, moving into a care facility, or splitting a household after a divorce. The term just means the sale covers an entire estate’s worth of belongings.
How estate sale companies work
According to Consumers’ Checkbook:
- Commission: companies typically keep 30 to 50 percent of sales, often on a sliding scale, with a lower percentage for larger estates.
- Is it worth it? A home generally needs about $3,000 or more in furnishings and household goods to be worth a professional sale, and many companies set minimum fees.
- Timing: most sales run two or three days, often Thursday or Friday through the weekend, with discounts on later days.
- Payment: the family usually gets paid two to three weeks after the sale.
- Contracts: remove anything you want to keep before you sign, because many contracts make everything in the house available for sale. Ask whether cleanout of unsold items is included.
There’s no license or certification for estate sale companies, so ask for references and get everything in writing.
How to prepare for an estate sale yourself
- Set aside what the family wants to keep and anything with legal or personal importance, like papers and photos.
- Check local rules. Some cities require a permit for any home sale. Here’s how garage sale permits work.
- Research valuable items. Look up sold prices for antiques, jewelry and collectibles, or get an appraisal.
- Price everything and group items by room. Use our garage sale pricing tips for everyday items.
- Advertise on local estate sale sites, Facebook Marketplace and Craigslist with lots of photos.
- Plan for security. Close off rooms that aren’t part of the sale, keep cash secure and have helpers watch each room. See our garage sale safety tips.
- Plan the last day. Discount everything left, then donate or arrange a cleanout. Here’s how to donate unsold items.
Estate sale vs. auction
At an estate sale, items have set prices and shoppers buy them on the spot. At an auction, buyers bid against each other, either live or online. Auctions can bring more for rare antiques and collections, while estate sales work better for a full house of everyday items.
What sells best at estate sales?
Furniture, tools, kitchenware, jewelry, art, vintage clothing, books, records and collectibles all sell well. Mid-century furniture and good-quality hand tools are especially popular with dealers and resellers. If you’re shopping to resell, see our list of items to flip.
Can you negotiate at an estate sale?
Sometimes. Prices are firmer on the first day, but many companies discount 25 to 50 percent on later days, and staff may accept reasonable offers on big items near the end.
Related guides: moving sale tips.